The arithmetic, in the open
Practice valuation calculation, step by step
The calculation has five steps: collections, overhead, an associate allowance and add-backs to get to adjusted EBITDA, then a multiple that depends on the buyer. For one dentist buying one general office in 2025, that multiple is 3×–4.25×, median 3.5×.
Below is each step with the arithmetic, a worked example on a $1,200,000 office, and a calculator that runs the same steps on your numbers.
The valuation account is free. No card. Read-only access to your books, always.
Step 1: start with trailing-twelve-month collections
Use the last twelve months of money collected, not production and not a calendar year that ended eight months ago. Buyers underwrite on collections because that is what pays the loan. If your collections rate is below 98%, the gap between production and collections is the first thing a buyer will ask about.
Step 2: subtract overhead to get operating profit
Dental overhead is every cost of running the office except the owner-doctor's own pay: staff, supplies, lab, rent, marketing, equipment. A general office typically runs 62%; specialties run lower. Collections × (1 − overhead) is operating profit before the owner is paid.
Step 3: subtract an associate allowance, add back the owner's extras
A buyer has to pay a dentist to do your clinical work, so about 17% of collections comes off. Then the add-backs go back on: expenses that stop when you leave, such as a personal vehicle, continuing education, travel, a family member on payroll, or a one-time write-off. The result is adjusted EBITDA, which for a typical general office lands near 21% of collections.
Add-backs are where valuations are argued. A buyer accepts an add-back that is documented and clearly personal; a buyer rejects one that looks like a cost the practice still has to carry. The app reads your P&L line by line and marks each candidate so you can see the case for it.
Step 4: pick the multiple for the buyer in front of you
The multiple is set by who is buying. An individual dentist is financing the purchase and keeping one office; a platform buyer is adding it to a group and can run it with shared systems. The 2025 rows for a single office:
| Buyer | EBITDA multiple (low – median – high) | Share of collections |
|---|---|---|
| One dentist buying one office | 3× – 3.5× – 4.25× | 60% – 75% – 95% |
| A partner buying in | 3.3× – 3.85× – 4.68× | 66% – 83% – 105% |
| A platform or private-equity buyer | 4× – 6× – 8× | 60% – 75% – 90% |
Step 5: the result is a range, and the range is the answer
Multiply adjusted EBITDA by the low, median and high multiple. The low end is what a buyer pays when the books, the team or the lease give them a reason to discount; the high end is what a buyer could pay if none of those reasons exist. Here is the whole calculation on one office:
| Step | Arithmetic | Result |
|---|---|---|
| Collections, trailing twelve months | Money actually collected, not production | $1,200,000 |
| Operating profit | $1,200,000 × (1 − 62% overhead) | $456,000 |
| Associate allowance | 17% of collections to pay a dentist to do your clinical work | − $204,000 |
| Adjusted EBITDA | 21% of collections | $252,000 |
| Low end | $252,000 × 3× | $756,000 |
| Median | $252,000 × 3.5× | $882,000 |
| High end | $252,000 × 4.25× | $1,071,000 |
| Cross-check | 75% of collections | $900,000 |
Why the rule of thumb gets this wrong
The common shortcut, 70% of collections, skips steps two and three. Two offices collecting $1,200,000 get the same answer even when one runs 57% overhead and the other 67%; on the arithmetic above, that 10-point gap is worth about $420,000 of price. The shortcut also gives the same number to a partner and to a platform buyer, who in 2025 paid very different multiples.
Use the share of collections as a cross-check only. At the median, it comes to 75% of collections for a general office, which is why the two tables agree for a typical practice and disagree for yours.
Run the calculation on your numbers
The same five steps, on your collections and overhead. Nothing is submitted. The app does this on your actual P&L, line by line, with the add-backs found for you.
How we get to a number
Buyers price a practice on EBITDA. Earnings after a market-rate dentist. Times a multiple. The multiple depends on the buyer. And on how many offices. We use 2025 transaction multiples. Same table as the app. Adjusted for specialty.
- Individual buyer — a dentist buying one practice. Most single offices sell this way.
- Partnership — an associate buying in. Or two dentists together.
- DSO / platform — pays for scale. Every multi-location practice. Single offices above about $1.2M.
DPC valuation dataset (2020–2025 dental transactions), 2025 rows.
What decides where you land inside the range
The calculation above gets you to the range. The eight factors below decide where you land in it, and each one can be measured from your practice data. The app scores them and prices them, so the plan for the next two quarters is a list with dollars attached.
- Financial quality: books that tie out, add-backs a buyer will accept, and a margin that holds up
- Patient base: active patients seen in the last 18 months and new-patient flow, not the chart count
- Staff and key-person risk: how much production leaves with you, and whether the team stays
- Payer mix: fee-for-service and strong PPO schedules versus heavy write-offs at the same collections
- Capacity: open operatories, open days and unscheduled treatment a buyer can execute in year one
- Facility and lease: years of term or options left, rent as a share of collections, equipment age
- Market: the demographics and competition around the office, which no amount of work moves
- Transition: how long you will stay, and how much of the referral base follows the practice rather than you
What happens after you create the free account
Run the same calculation on your real P&L, free
The account runs on an uploaded P&L or a read-only QuickBooks connection, and it stays free. A practice-management connection through Sikka — production, collections, providers and payers — is something we set up with you when you sell with us.
- 1
Create your free account
Three short screens: you, your practice, your numbers. About two minutes. Nothing is published anywhere, and no card is asked for.
- 2
Connect QuickBooks, or upload a P&L
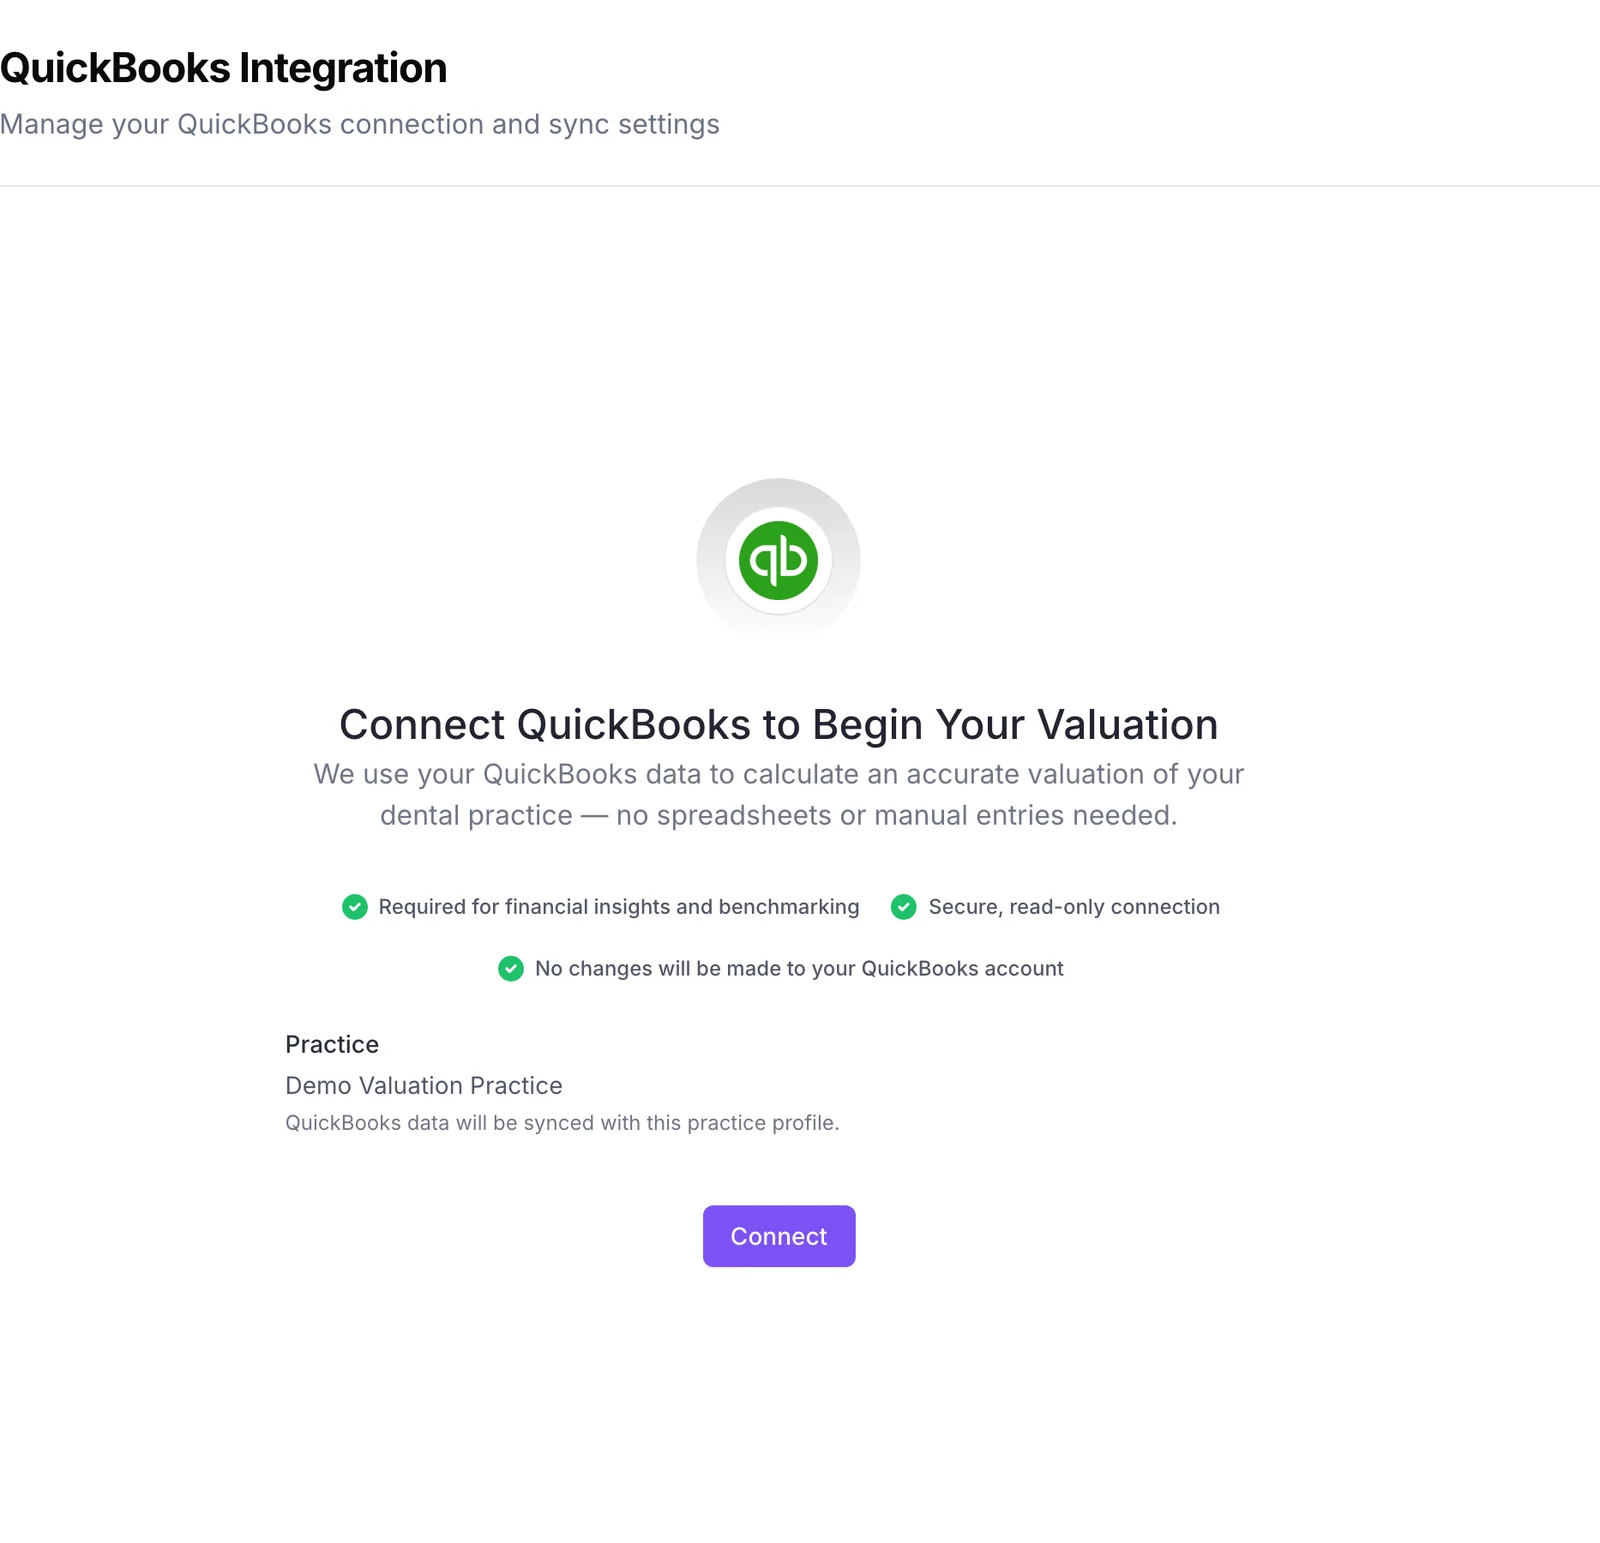
Connect QuickBooks Online and we read your chart of accounts and Profit & Loss. The connection only ever reads; nothing in your books is changed. No QuickBooks? Upload the Excel, CSV or PDF export your accountant already sends you.
QuickBooks: a read-only connection. - 3
We classify the accounts and find the add-backs
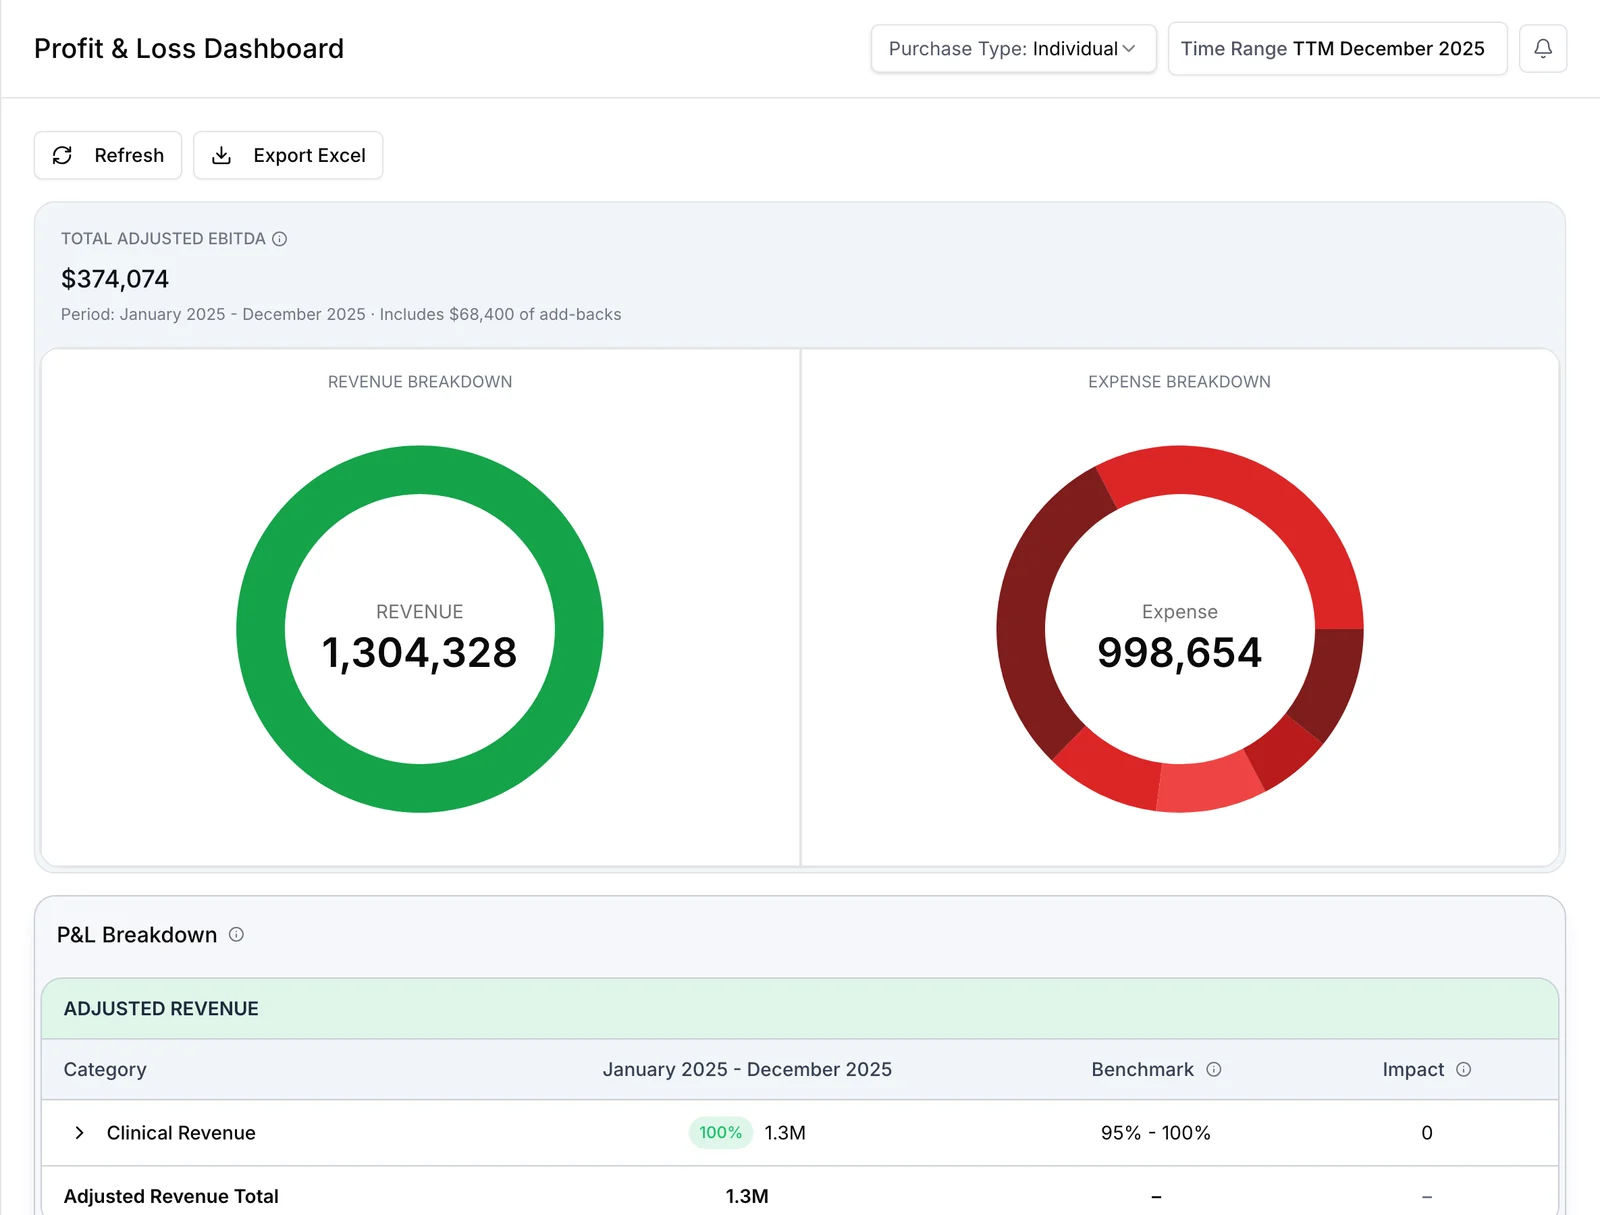
Every account is mapped to a dental category and compared with industry benchmarks. Owner add-backs are called out line by line, and you can review every mapping.
Profit & Loss, benchmarked line by line. - 4
Your valuation and scorecard appear
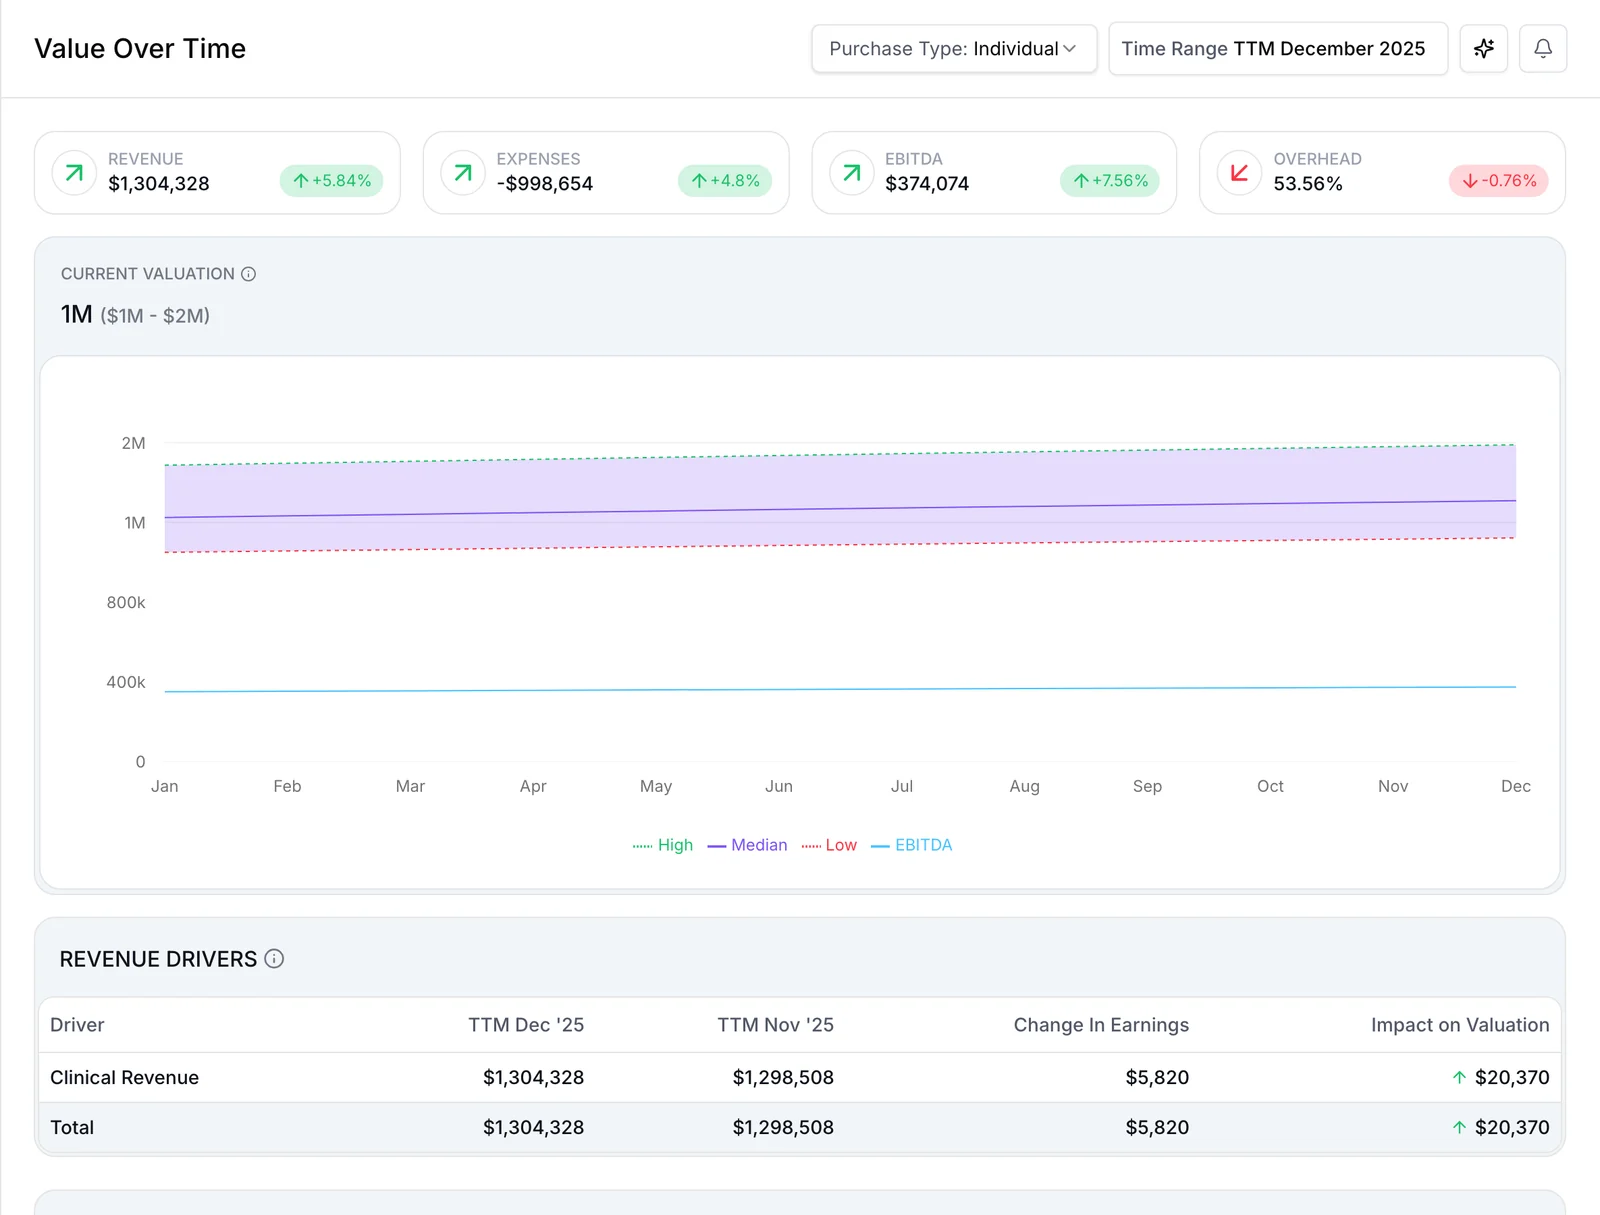
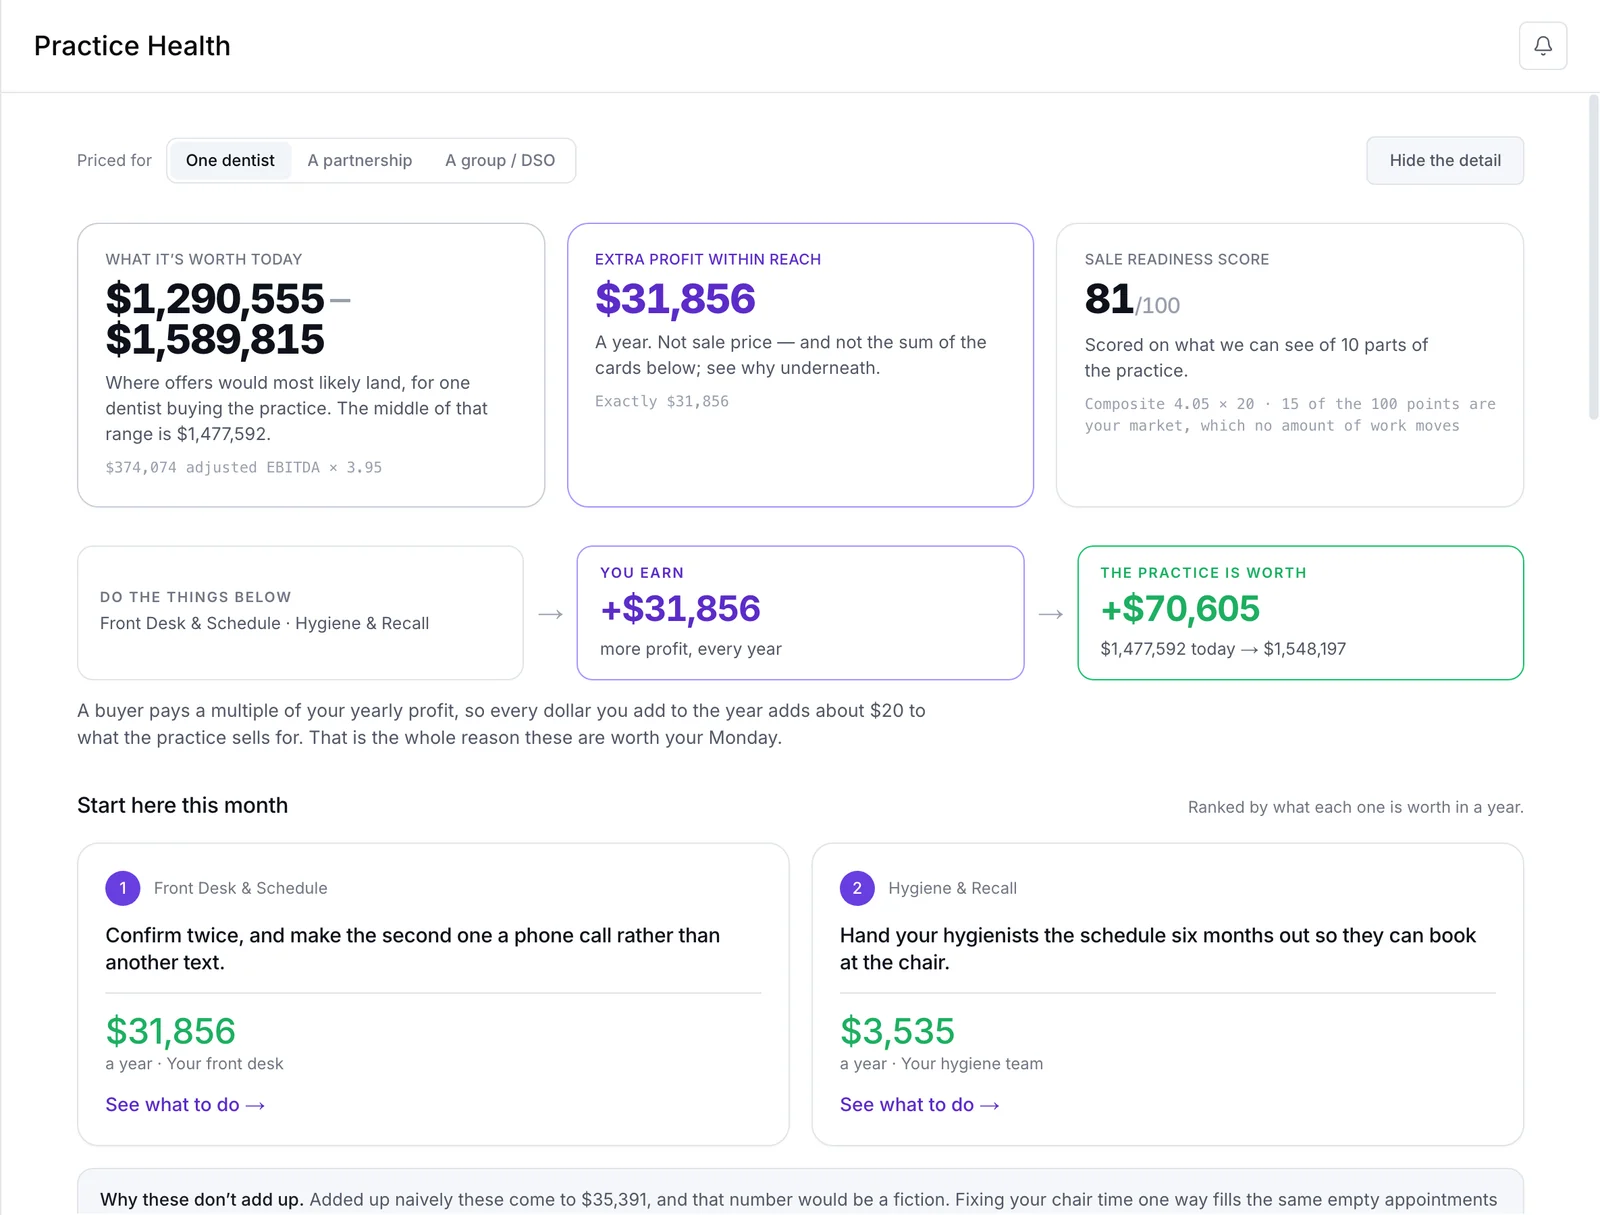
A value range by buyer type on your adjusted EBITDA, charted month by month, and a Practice Health score with the three levers worth the most to you this year. It updates every time your books do.
Value over time, by buyer type.
Questions about the calculation
What is the formula for a dental practice valuation?
Adjusted EBITDA × a multiple set by the buyer type. Adjusted EBITDA is collections − overhead − an associate allowance (about 17% of collections) + owner add-backs. For one dentist buying one general office in 2025 the multiple is 3×–4.25×, median 3.5×.
Should I use production or collections?
Collections. Production is what was scheduled and billed; collections is the money that arrived. Lenders size the loan on collections, so buyers do too. A collections rate under 98% is itself a question a buyer will ask.
What counts as an add-back?
An expense the buyer will not have to pay: the owner's vehicle, personal travel, continuing education beyond what the practice needs, a family member on payroll, a one-time write-off. Rent above market paid to an entity you own is an add-back too; rent below market is the opposite and gets subtracted. Documented and clearly personal is what a buyer accepts.
Does the calculation change for a specialty practice?
The steps are the same; the inputs differ. Specialty overhead is usually lower than general dentistry, and orthodontic, oral surgery and periodontal offices clear a premium on the multiple. The calculator on this page applies both adjustments and states the basis for each.
What is actually free?
The instant estimate on this page is free and needs no account. The full valuation account is free too: create it, upload a P&L or connect QuickBooks read-only, and the valuation, the benchmarked P&L and the scorecard are yours, with nothing published and no card asked for. The only fee on this site is the brokerage fee, paid at closing if you choose to sell the practice with us.
Does Dental Practice Connect change anything in my QuickBooks?
No. Every connection is read-only, and that is enforced in the code rather than promised: only read requests can leave the product. Intuit's permission screen offers no read-only option, so it will list full accounting access when you connect; we never send a write. We read your books to value the practice; we never edit them.
Want the calculation checked on your numbers?
Send the question and where you are in the process. The reply is the arithmetic on your figures, with the basis for each step.
Keep reading
Dental practice valuation
How a practice is priced: adjusted EBITDA, the multiple by buyer type, and what buyers discount.
What's my dental practice worth?
The short answer, the five numbers that decide it, and a free range in about a minute.
Sell a dental practice
Who buys, what each buyer pays, the timeline that protects your price, and a DSO offer vs. a private sale.
2025 dental practice multiples
The transaction table behind every number on this page.